1300 710 863 | hello@aboutbusinessbooks.com.au
1300 710 863 | hello@aboutbusinessbooks.com.au

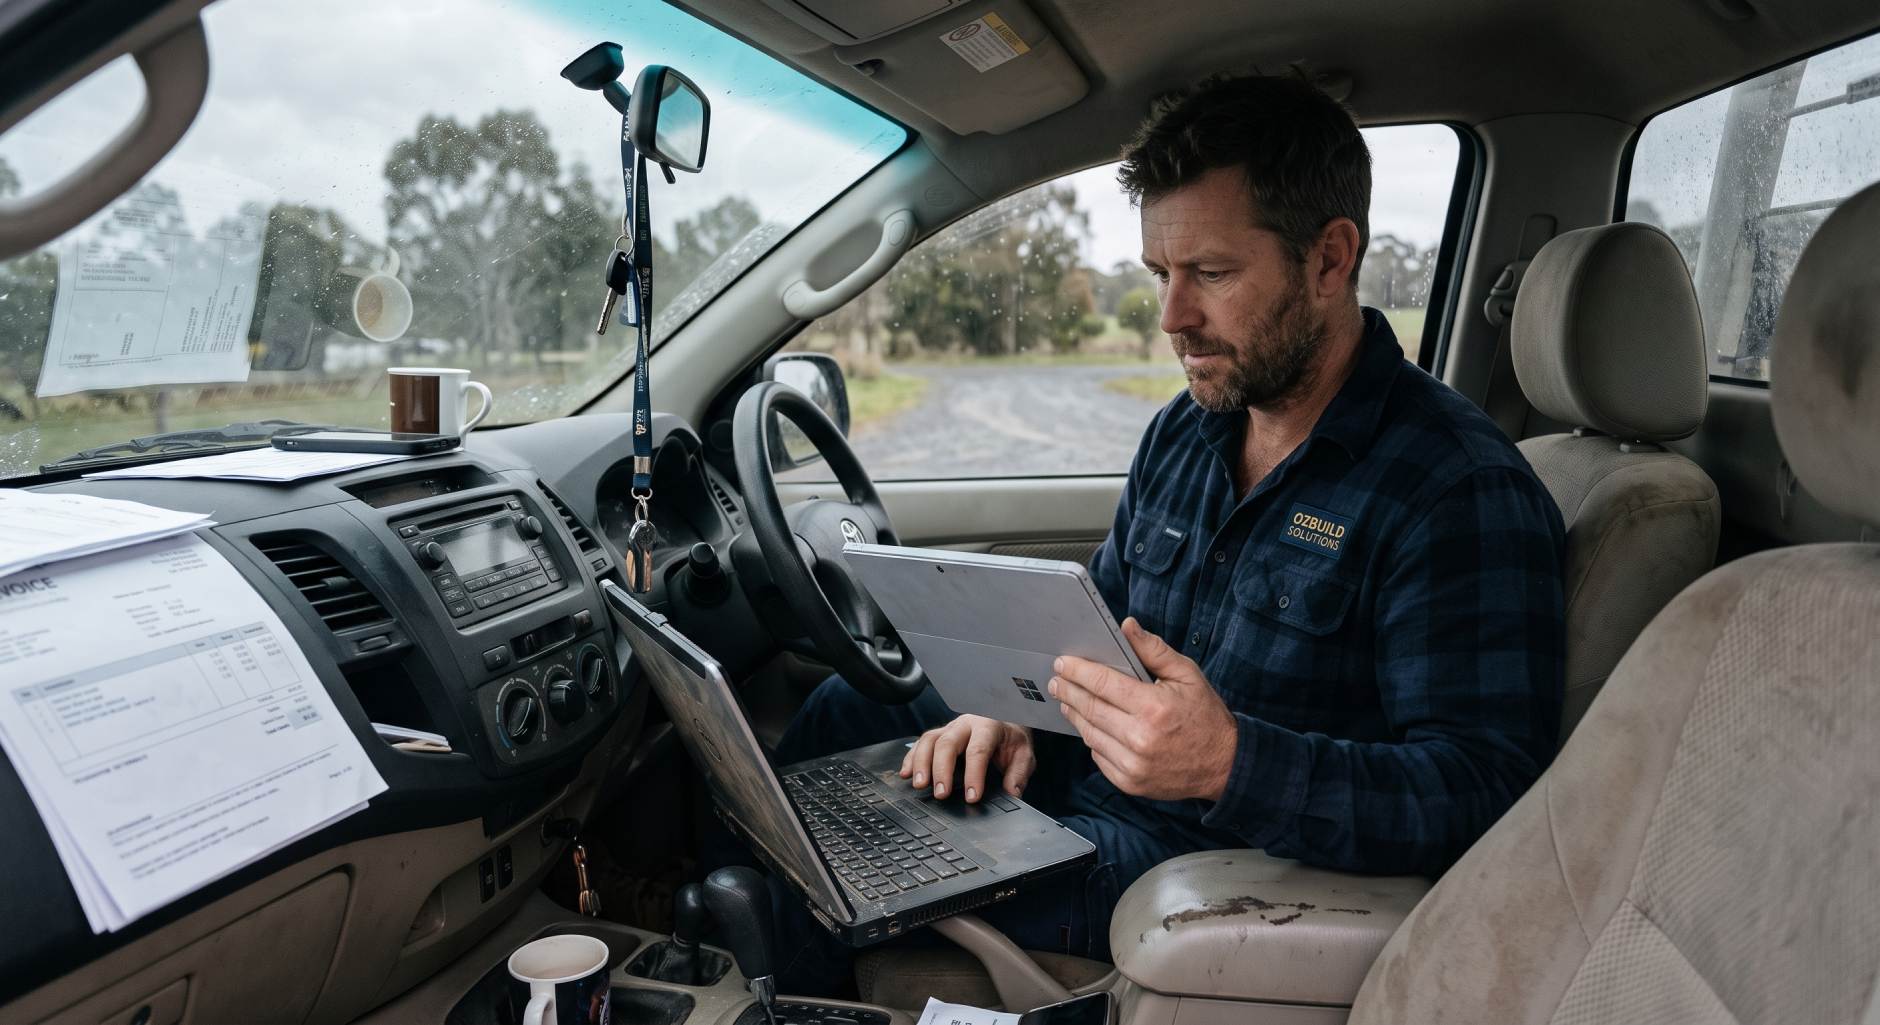
It usually starts small. Work is flat out, the receipts end up in a shoebox, and one BAS deadline slips by. If you run a business on the Sydney or on the Central Coast and a missed quarter has turned into several, here is exactly what falling behind on your BAS lodgements actually costs you, and how to get back on track.
Missing one BAS is stressful enough. The ATO does not wait quietly while you get organised, penalties and interest start building from the day it is overdue, and each additional missed quarter adds another layer on top. What starts as one overdue lodgement can compound into thousands of dollars in penalties and interest within a year, and we see it happen to genuinely good Sydney and Central Coast business owners, not just disorganised ones.
The ATO can apply a penalty simply for lodging late, even if you do not end up owing any tax. For a small business, it works out to one penalty unit for each 28-day period (or part of one) your BAS is overdue, up to a cap of 5 penalty units. As of 1 July 2026, one penalty unit is $364, meaning an overdue BAS can cost $364 for each 28 days it is late, up to a maximum of $1,820 per lodgement. Medium and large businesses face higher multiples of the base penalty.
If you work with a Registered BAS Agent, a statutory safe harbour can protect you from this penalty, but it’s conditional, not automatic: you need to have given your agent everything they needed to lodge on time, and the late lodgement needs to be the agent’s error rather than yours. It’s one of the reasons having a registered agent in your corner matters.
If your overdue BAS comes with a tax debt attached, say you have collected GST but have not paid it across, the ATO charges interest on top, called the General Interest Charge. It compounds daily, and as of the July to September 2026 quarter it sits at the current ATO GIC rate per year.
Here is the part that catches people out: since 1 July 2025, GIC (and its cousin, the Shortfall Interest Charge) is no longer tax-deductible, regardless of which year the debt relates to. That makes carrying ATO debt more expensive than it used to be, and it is a good reason to deal with it rather than let it sit.
If you go quiet and do not lodge, the ATO will not just wait. Eventually they can issue a default assessment, their own estimate of what you owe, based on your industry and past lodgements, If the ATO issues a default assessment, speak with your tax agent about what it means and the steps available to you.
If your business is a company, this is the one to take seriously. Under the ATO’s director penalty regime, a Director Penalty Notice (DPN) can make you personally liable for the company’s unpaid PAYG withholding, superannuation guarantee charge, and net GST.
There are two versions. If your BAS and super reporting were lodged on time but just unpaid, you get a 21-day notice, you have 21 days from the date on the notice to pay, restructure, or begin winding up the company, and doing any of those remits the penalty. But if the BAS or IAS is not lodged within 3 months of its due date (or the SGC statement isn’t lodged by its due date), it becomes a lockdown notice, you are personally liable straight away, and paying the debt in full is the only way out.
If a DPN debt is not addressed, the ATO can recover it the way they would any personal debt: garnishee notices to your bank or employer, offsetting your personal tax refunds, and ultimately legal action that can lead to bankruptcy. Separately, the ATO can also report business tax debts to credit bureaus once a debt exceeds $100,000 and is overdue by more than 90 days, provided you aren’t actively engaging with them, which can affect your ability to raise finance. It’s a genuinely serious position to be in, which is exactly why lodging on time (even if you cannot pay yet) matters so much, it keeps you in 21-day territory instead of lockdown.
Falling behind on BAS lodgements is fixable, but the cost compounds the longer it sits: FTL penalties, non-deductible GIC interest, default assessments, and for company directors, personal liability under a DPN. If you’re several quarters behind, our registered BAS agents can deal with the ATO on your behalf, do the forensic cleanup, and get your lodgements current. Get in touch for a confidential, judgment-free chat.
Penalty and interest figures current as of August 2026 (Q3 2026 GIC rate; penalty unit value effective 1 July 2026). The GIC rate changes quarterly and the penalty unit is re-indexed periodically – confirm current figures with the ATO.